

Brigit: Cash Advance & Credit
by Brigit
4.8
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.8
- Price
- Free
- Download
- 10.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
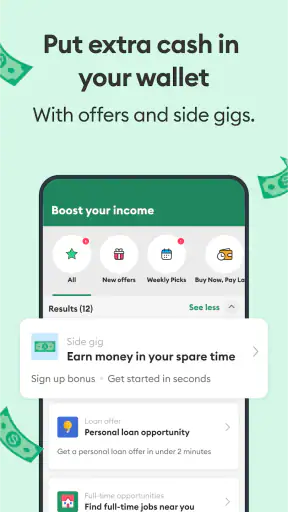
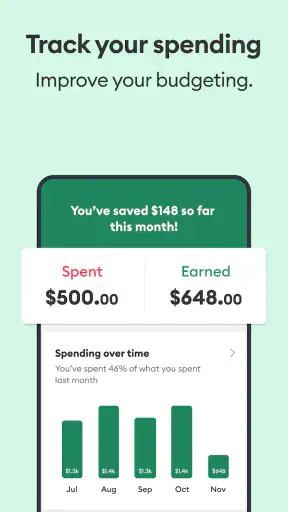
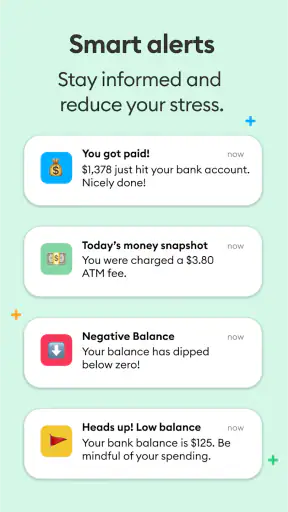
 Analysis by Getfullapps
I look at Brigit as a finance app built around short-term flexibility rather than long-term money management. It brings together cash advances, personal-loan options, credit-building tools, and ways to earn money in one place, which can be useful when a regular paycheck arrives just after an important bill. My overall impression is that it is most valuable when used as a carefully planned bridge, not as a permanent replacement for an emergency fund or a stable budget.
The app is free to download and is rated for Everyone, so it is approachable for a broad audience. It comes from Brigit, a developer focused specifically on this kind of financial service, and its popularity is substantial: it has passed 10 million installs and holds a 4.8 average from roughly 377 thousand ratings. Those figures suggest that many people find the service useful, but they should not replace personal checking. A finance app can be popular and still be a poor fit for someone whose income, account history, or borrowing needs do not match its process.
How Brigit fits into real financial decisions
I use this section to frame Brigit around the decision that matters most: whether a cash-flow gap is brief and manageable, or a sign that the monthly plan needs a different fix. That distinction helps me decide what to check before opening the app and keeps convenience from driving the choice. From there, I can build a repeatable routine around the settings and account details that deserve attention.
A useful bridge, but not free money
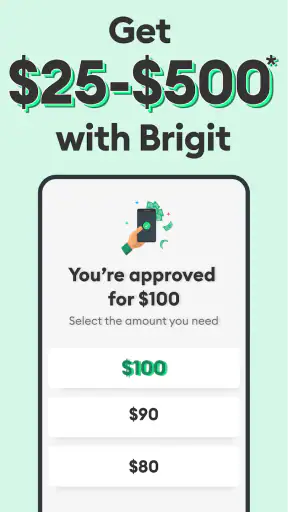
The central appeal is the possibility of requesting an instant cash advance in the range of $25 to $500. In everyday terms, that could help someone cover groceries before payday, avoid a late utility payment, or handle a small car expense when the timing is awkward. I find this use case more convincing than treating the app as a general spending account. The amount is designed around short gaps, so the best experience comes from knowing exactly when incoming money will arrive and what will repay the advance.
That distinction matters. A cash advance can solve a timing problem, but it does not solve an income problem. If every pay cycle ends with the same shortage, repeatedly taking advances can make the next cycle feel tighter. I would only use this kind of service after writing down the repayment date, the amount expected in the linked account, and the bills that must clear first. That simple check is more important than the speed of the request.
Brigit also presents personal loans, credit-building tools, and earning opportunities, so it is broader than a single-purpose payday alternative. Still, those areas should be considered separately. A small advance may be appropriate for a one-off cash-flow mismatch, while a personal loan is a larger commitment that deserves a slower comparison with other lenders. Credit-building is a longer-term goal, and earning tools are not a substitute for guaranteed income. Keeping those purposes distinct prevents the app from becoming a single button for every financial worry.
What the public response tells me—and what it does not
The app has been available since April 16, 2018, and the current release is version 1177.0. It supports devices running Android 8.1 or later. Its longevity and large review base make it easier to judge than a brand-new finance app, because there is a broader record of people using it over time. I still treat ratings as a starting point rather than proof that every user will receive the same result.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
People often judge a finance app by whether money arrives when expected, whether repayment is understandable, and whether account linking works without confusion. Those are practical trust questions. A high rating can indicate that many users have had a satisfactory experience, but it cannot tell me whether the available amount, eligibility decision, or repayment arrangement will suit my own circumstances. I would read the current in-app terms carefully before accepting any offer, especially when moving from a small advance to a loan product.
Trust begins with the choices shown on screen
For a finance app, I pay more attention to visible choices than to polished presentation. Before connecting an account or requesting money, I want to see what information is being requested, why it is needed, what action I am authorizing, and how I can stop using the service. I also want the repayment details to be clear enough that I can understand them without guessing.
That is where Brigit should be approached deliberately. The app may put several services beside one another, but I would not move through each option automatically. I would open only the feature I actually need, review the displayed conditions, and avoid accepting additional products simply because they appear in the same dashboard. The safest workflow is to make one decision at a time and save a record of what you agreed to.
I would also check the account controls after setup rather than assuming that deleting the app ends every relationship. A responsible routine includes reviewing linked accounts, notifications, repayment settings, and any recurring access that the app presents. If a control is unclear, I would pause and look for the explanation inside the app before proceeding. That is not unnecessary caution; financial permissions deserve more attention than permissions for a casual game or social app.
Account linking deserves a slower look
Brigit’s usefulness depends on personal financial information, so the most sensitive moment is usually the beginning: creating an account, connecting a bank account, and reviewing eligibility. I would complete that process only on my own device and a trusted connection. I would also make sure that the bank account selected is the one I actually intend to use, since confusing a primary account with a savings account could create avoidable repayment problems.
Before confirming a connection, I would read the permission screen from top to bottom. I would look for the categories of information involved, the purpose of access, and any option to change or remove the connection later. I would not treat a familiar bank name or a fast setup as a reason to skip those details. In financial services, convenience is useful only when I still understand what I am authorizing.
Another good habit is to review the app after the first successful transaction. I would check whether the balance, repayment date, and linked account are displayed as expected. If anything looks different from what I remember approving, I would stop using the feature until I understood the discrepancy. This is a concrete advantage of taking screenshots or keeping confirmation emails: they give me a personal reference instead of relying on memory during a stressful week.
Notifications can help, but I would manage them
Alerts can be valuable when a repayment or account event matters, yet too many financial notifications can become background noise. I would keep alerts that help me track an advance or an important account action and reduce anything that encourages impulsive browsing. The goal is not to ignore the app; it is to make sure a notification prompts a deliberate check rather than an immediate borrowing decision.
I would also separate reminders from recommendations in my own mind. A reminder about an upcoming obligation is practical. A suggestion to explore another product is a sales prompt, even if it is presented neatly. That distinction is easy to lose when several money features share one interface. I prefer to open the app with a specific question—“What do I owe, when, and from which account?”—instead of scrolling until I find a new offer.
Using an advance without creating a second emergency
A realistic example would be a worker whose paycheck is due on Friday but whose electricity bill is scheduled for Wednesday. If the person has a reliable Friday deposit and the bill is otherwise manageable, a small advance could bridge those two days. I would first compare the advance amount with the exact bill, leaving no reason to request more than necessary. Then I would confirm that the Friday deposit will remain available after rent, food, transport, and other automatic payments.
The less obvious risk is not the initial request; it is what happens after repayment. If the advance removes money that was already assigned to essentials, the user may need another advance immediately. To avoid that loop, I would write a mini cash-flow plan for the next two paydays, not just the next two days. If the numbers show that repayment leaves no room for necessities, I would look for a bill arrangement, employer support, community assistance, or a slower budgeting solution instead.
I would also avoid using an advance for discretionary purchases. The app may make a small amount feel harmless, but the repayment still arrives later. Using borrowed cash for a planned purchase weakens the main reason to use the service: handling a short, unavoidable timing gap. That is one of the clearest boundaries I would set for myself.
Credit-building requires patience and careful reading
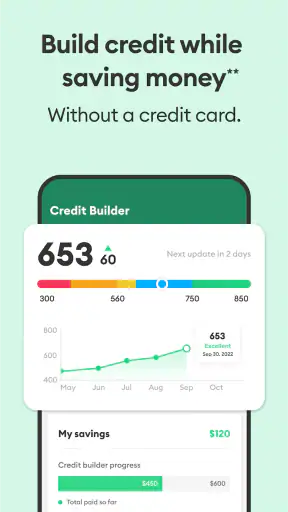
The credit-building side may appeal to someone trying to establish a stronger financial record, but I would judge it by its actual terms rather than by the label alone. Credit products can involve specific requirements, reporting practices, payment schedules, or account behavior that need to be understood before enrollment. I would read every explanation presented in the app and confirm how the product fits with my existing obligations.
This is also an area where expectations should stay realistic. A credit-building tool is not an instant repair for missed payments or high balances elsewhere. If I were already struggling with several accounts, I would first organize due dates and contact creditors directly where possible. Brigit could be one part of a longer plan, but I would not choose it solely because I hoped for a rapid change in my credit profile.
Personal loans call for comparison shopping
The personal-loan option broadens Brigit’s reach, but it also raises the stakes. For a larger borrowing decision, I would compare the total repayment, schedule, and conditions with offers from a bank, credit union, or other established lender. The important question is not simply whether an application is convenient. It is whether the loan remains affordable after housing, food, transport, insurance, and existing debt are paid.
I would be particularly careful about moving from an urgent cash need into a longer obligation. A fast application can feel reassuring when money is tight, yet speed does not make a loan inexpensive or suitable. If I could wait, I would take that time to calculate the total cost and consider whether a smaller amount would solve the actual problem. If I could not explain the repayment plan in my own words, I would not accept it.
Who will appreciate the app most
Brigit makes the most sense for someone with a predictable income pattern, a verified short-term gap, and enough discipline to treat an advance as a planned transaction. It may also suit a user who wants several financial tools in one app and is willing to inspect each product separately. The free entry point makes it easy to explore, while the Everyone rating and support for Android 8.1 or later make the basic installation accessible on many older devices.
I would recommend it more cautiously to someone with irregular income. Freelancers, seasonal workers, and people whose deposits change sharply from week to week may find it harder to predict repayment safely. The same applies to anyone whose account is already frequently overdrawn. In those situations, an advance can hide the underlying issue for a short time while making the next deposit less flexible.
I would skip it if I wanted a full investing platform, a detailed household accounting system, or a replacement for a traditional bank. Its appeal is concentrated around immediate cash flow, borrowing-related tools, credit-building, and earning options. Someone seeking long-term financial planning may be better served by a budgeting tool that focuses on categories, goals, and spending analysis rather than short-term access to money.
How it compares with familiar alternatives
Compared with asking a bank for an overdraft extension, Brigit may feel more focused on the specific problem of getting through a short gap. A bank, however, may offer a broader view of the customer’s accounts and existing services. Compared with a credit union, Brigit can be more convenient to explore from a phone, while a credit union may be preferable for someone who wants personal guidance and a longer-term relationship.
Compared with a credit card, a cash advance can feel more contained because it is tied to a particular short-term need rather than an open revolving balance. On the other hand, a credit card may offer a clearer billing cycle for someone who already understands how to pay it in full. Neither option is automatically safer; the better choice depends on the repayment certainty and the cost shown before acceptance.
Compared with payday lending, the smaller, app-based experience may appear less intimidating, but I would still read every condition and avoid assuming that a modern interface means low risk. The right comparison is the complete obligation, not the friendliness of the screen. If a local assistance program, employer advance, family arrangement, or bank solution can cover the same short gap without creating a difficult repayment burden, I would consider those first.
A practical routine for responsible use
My preferred routine would begin outside the app. I would identify the exact expense, confirm the amount needed, and check the next two incoming deposits. Only then would I open Brigit and review the available option. I would read the confirmation screen carefully, note the repayment date, and keep the transaction record somewhere I can find it.
Afterward, I would check the linked account and upcoming bills before spending the remaining balance. I would not assume that a successful advance means the rest of the month is safe. If the transaction exposed a recurring shortfall, I would treat that as a signal to change the budget or seek assistance, not as an invitation to repeat the same action automatically.
For privacy and control, I would periodically revisit connected accounts and notification choices. I would remove access I no longer need through the available account controls and avoid leaving old financial connections in place simply because they are convenient. I would also keep the app updated, since the current version is 1177.0, while remembering that an update does not remove the need to review permissions and terms myself.
Where the experience may create friction
The main friction is that financial urgency encourages fast decisions, while responsible borrowing requires slow reading. Brigit places several types of help in one destination, which is convenient but can make it harder to maintain a clear mental boundary between an advance, a loan, a credit-building service, and an earning feature. I would resist treating them as interchangeable.
Eligibility and available options can also be personal rather than universal. A user may install the app expecting a particular amount or feature and then discover that the displayed choices do not match the immediate need. That possibility is another reason not to build a bill-payment plan around money that has not yet been approved and clearly scheduled.
Finally, the app cannot remove the emotional pressure behind a cash shortage. A clean interface may make borrowing feel simple, but the repayment still affects the user’s real account. I value Brigit most when it helps me make a small, informed adjustment; I value it least when it tempts me to postpone a larger financial decision.
My cautious verdict
Brigit is a credible option to investigate when the problem is a specific, temporary gap and the repayment plan is already clear. Its combination of advances, personal-loan access, credit-building, and earning tools gives it more range than a single-purpose cash app. The strong public response and long availability add useful context, while the free price makes initial exploration straightforward.
My recommendation comes with a firm condition: use the app with a written plan, inspect every permission and product choice, and treat the repayment date as seriously as the original emergency. I would not use it to fund routine overspending, cover an income shortfall that repeats every month, or accept a loan without comparing its full obligation with alternatives.
For someone who needs a carefully controlled bridge and is comfortable reviewing financial details on a phone, Brigit may be practical. For someone seeking comprehensive budgeting, personal financial counseling, or a solution to persistent debt, another route is likely better. In my experience, the app earns consideration not because borrowing is effortless, but because it can be useful when the user keeps control of the decision from beginning to end.
Pros
- Offers fast cash advances without hassle.
- User-friendly interface for easy navigation.
- Helps improve credit with regular updates.
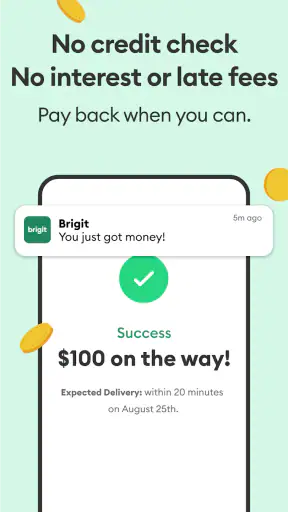
- No hidden fees or interest charges.
- Budgeting tools enhance financial planning.
Cons
- Limited to U.S. residents only.
- Requires a monthly subscription fee.
- Cash advances have a $250 limit.
- Not available for all banking institutions.
- May affect credit score temporarily.
FAQs for Brigit: Cash Advance & Credit
What is Brigit: Cash Advance & Credit and how does it work?
Brigit is a financial app that offers cash advances and credit-building tools to help users manage their finances more effectively. It provides small, interest-free loans to bridge gaps between paychecks and offers credit monitoring and budgeting features to improve financial health. Users connect their bank account to the app for accurate insights and personalized recommendations.
Is Brigit safe to use, and how does it protect my personal information?
Yes, Brigit is safe to use. It employs bank-level security measures, including 256-bit encryption, to protect your personal and financial information. The app does not sell your data to third parties, ensuring your privacy is maintained. Users can feel confident that their data is secure while using Brigit's features.
Are there any fees associated with using Brigit?
Brigit offers a free version of the app, but to access premium features like cash advances and credit-building tools, users need to subscribe to Brigit Plus. The subscription fee is typically around $9.99 per month. This fee allows users to access additional features, which can help them improve their financial management and credit score.
How quickly can I receive a cash advance from Brigit?
Once your account is set up and verified, you can request a cash advance at any time. Brigit typically processes advances within one business day, and funds are directly deposited into your bank account. This quick turnaround helps users manage unexpected expenses effectively without incurring high-interest debt.
Can Brigit help improve my credit score, and if so, how?
Yes, Brigit can help improve your credit score. It offers a credit builder feature that reports your payments to credit bureaus, helping you build a positive credit history. By making consistent, on-time payments through the app, users can see improvements in their credit score over time, which can open up better financial opportunities.

Brigit: Cash Advance & Credit
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via info@hellobrigit.com, visit https://hellobrigit.com, or review their https://hellobrigit.com/privacy.










